Turn more mortgage Leads into funded loans
For consumer direct, retail, broker and wholesale teams: routing by state license, response clocks that match each lead source, Application visibility with your LOS staying authoritative, and recapture on the book you already own.
Built for the way your channel works
Eligible, then fast. License and state routing, timed offers, queue and claim, the unaccepted-Lead rule, aged-lead rework and source-to-funded reporting by marketplace.
The loan officer's first screen, preapproval-to-close follow-through, stalled-file views for the branch manager, and the referral partner's history on the Contact.
One company-owned Contact with many Leads, assignment history when an officer moves, and opt-outs that follow the person, around the LOS the shop already runs.
Broker and account-executive pipelines, territory routing, and re-engagement on the relationships you hold, with the same clocks and the same record.
Who owns each step
The CRM owns the work around the Lead. Customer Engagement carries the conversation. Your POS and LOS keep the application and the loan.
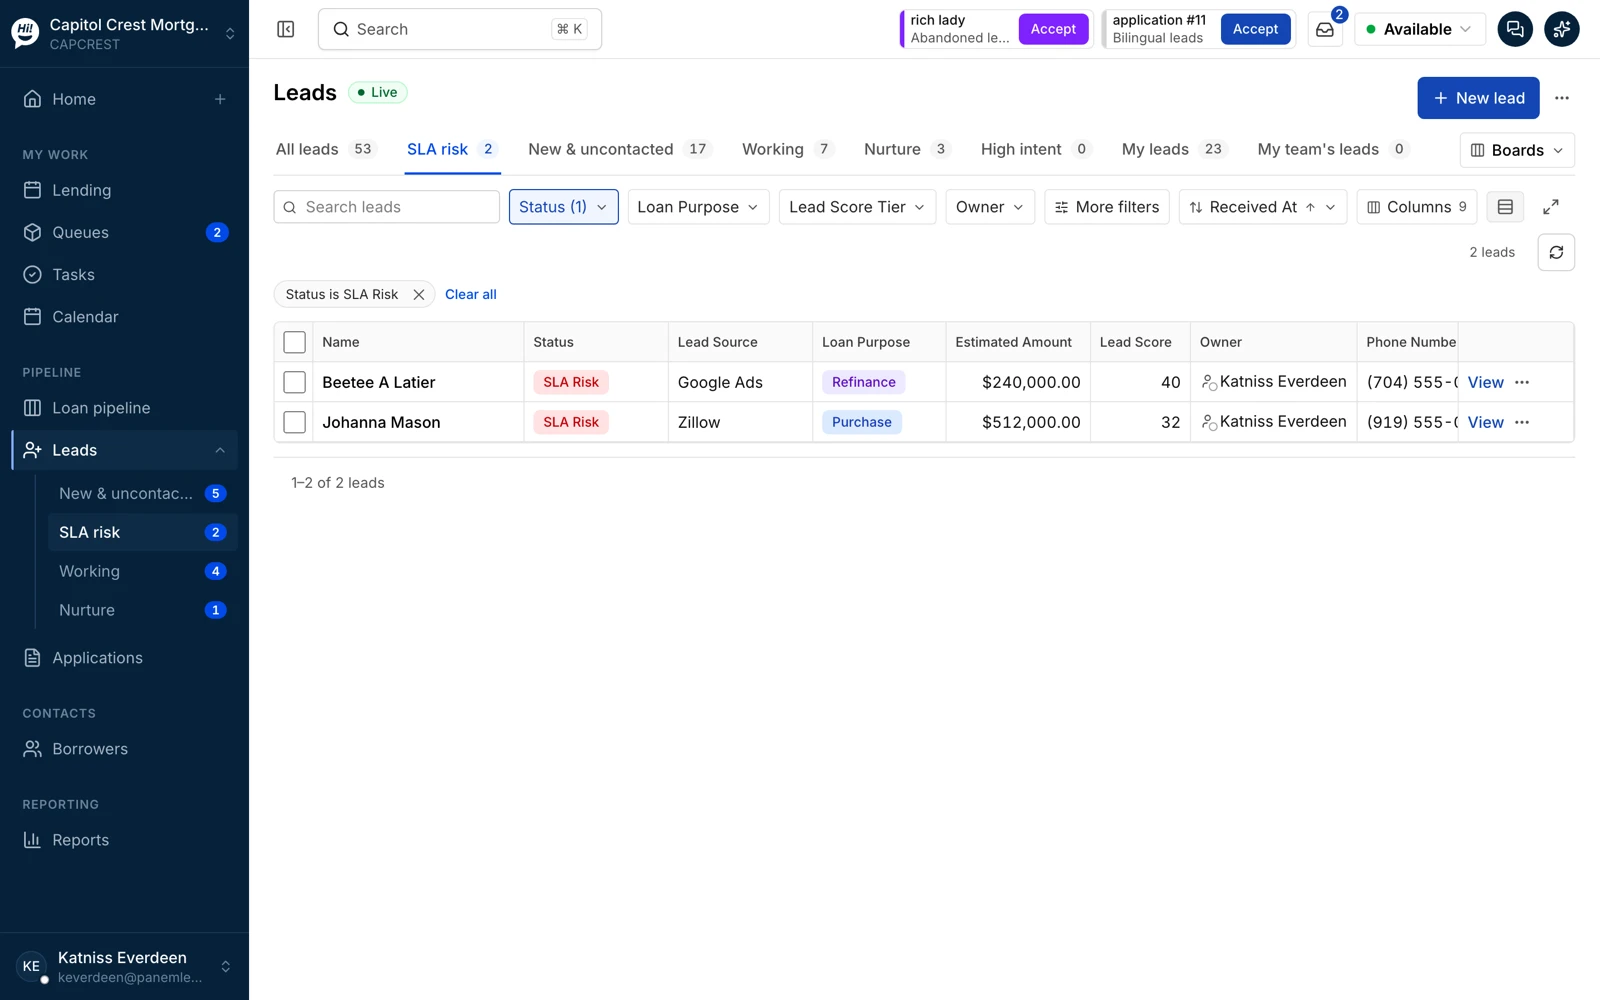
A clock per source, not one clock for everyone
A marketplace Lead and a past-client referral do not deserve the same clock. Service levels are set per source and per stage, business calendars keep them honest, and the SLA-risk view is where a manager starts the morning.
- New and uncontacted, SLA risk, working and nurture as saved views
- Escalation to the queue when a clock runs out
- Speed to lead and SLA attainment on the executive dashboard
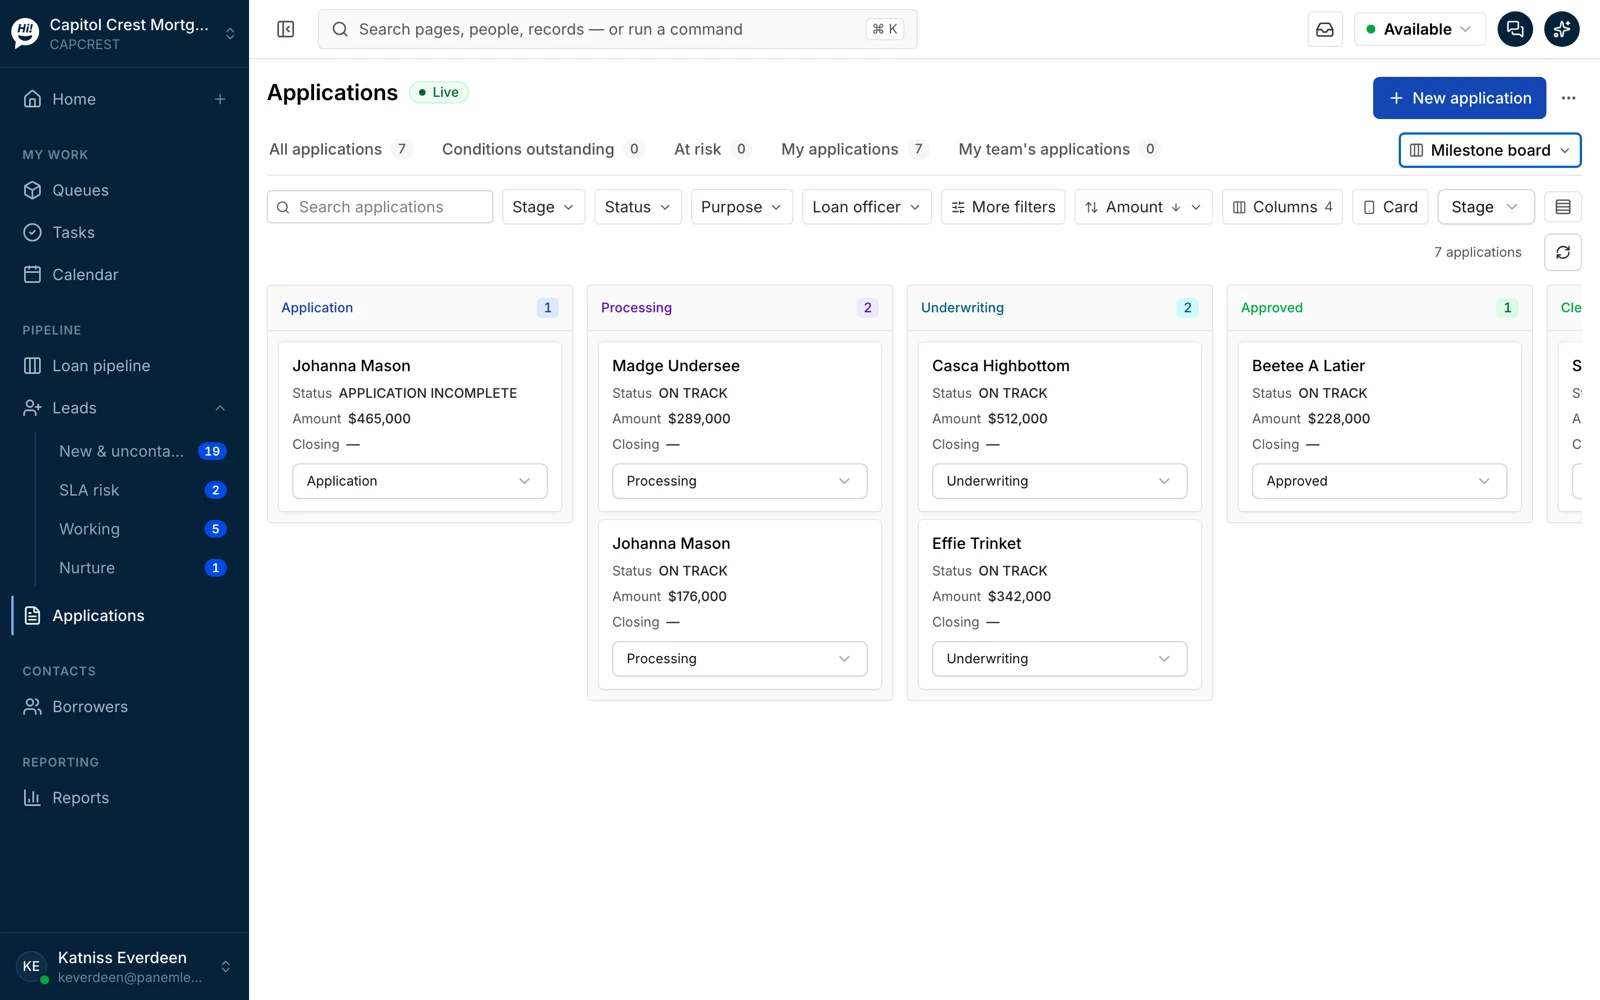
The file on a board, the LOS still in charge
Application, processing, underwriting, approved, clear to close. The board mirrors the LOS milestones so the loan officer and the processor see the same thing, and a stalled file is a tile on the dashboard, not a surprise at the weekly meeting.
- Milestone and stage views, conditions outstanding, at-risk files
- Post-close workflows start when the Application funds
- Retain and re-engage from the Contact, not from a spreadsheet
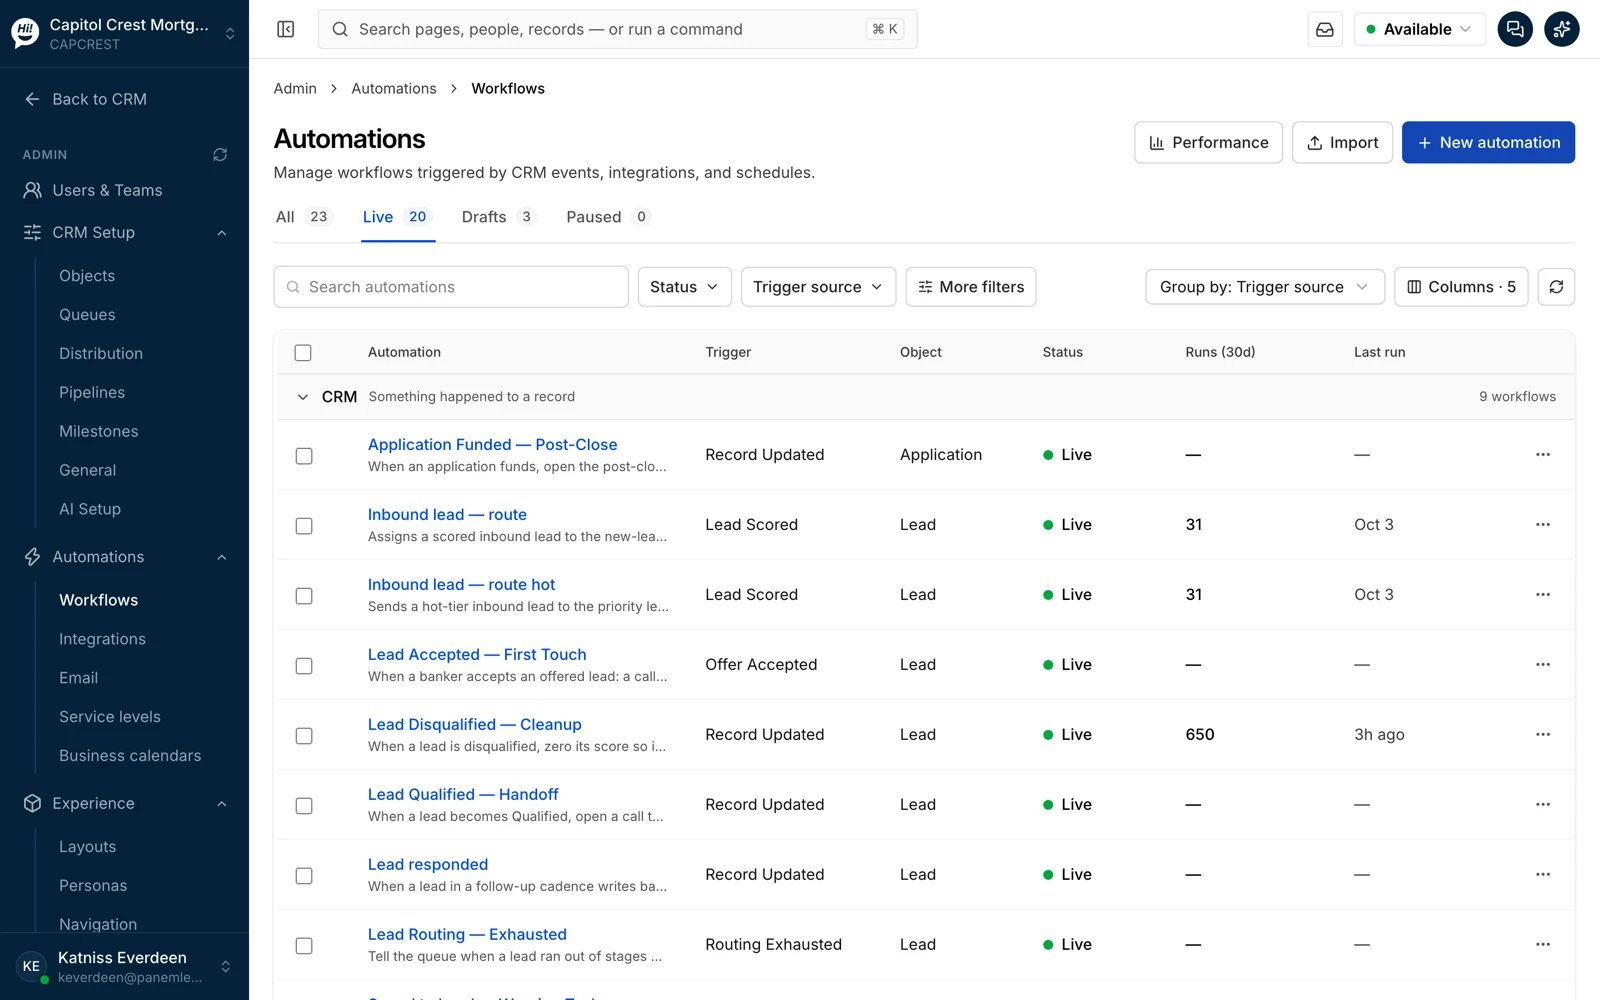
Lending workflows out of the box
Route an inbound Lead by score, send the hot tier to the priority queue, first touch when an officer accepts, cleanup when a Lead is disqualified, handoff when it qualifies, and the post-close sequence when the loan funds. Change what is yours; keep the rest.
System of action, systems of record
The LOS keeps the loan file. The POS keeps the application intake. The CRM keeps who owns the Lead, on what clock, and what happens next.
Marketplaces, web forms, landing pages, referral partners and the website itself, each with its own clock and attribution.
Applications and milestones mirrored into the CRM; what writes back is confirmed for your setup before the pilot.
SMS, voice, chat and email through Botsplash Customer Engagement, written to the Lead.
Calendars, e-signature, dialers, Salesforce or HubSpot, and custom integrations through the API.
Questions mortgage teams ask
Does Botsplash CRM replace our LOS?
No. The LOS stays authoritative for the loan file. The CRM mirrors the Application with its milestones so loan officers and managers see where it is and who moves it next, and it writes back what you decide it should.
What about our point-of-sale application?
The POS keeps the application intake. A started or abandoned application is a signal on the Lead, so the follow-up happens from the CRM with the right owner and the right clock.
How does routing by state license work?
Distribution rules read the licenses on each loan officer and the property or borrower state on the Lead, along with skill, branch and capacity. An ineligible officer never sees the Lead; an unaccepted Lead returns to the queue.
Is a home-equity inquiry from a past client a new customer?
No. It is a new Lead on the Contact you already have, with the history, consent and owner intact. Recapture and home-equity work queues start from the book you own.
Can we keep our marketing CRM?
Yes. Many teams keep a marketing platform for drip content and use Botsplash CRM for the execution: ownership, routing, clocks and the next step. We confirm what flows between them before a pilot.